Burst Pipe Insurance Claims: 9 Tips and What Your Policy Covers
Sage Southard manages the estimating department at Advanced Disaster Recovery, bringing seven years of restoration-industry experience to insurance estimating and large-loss documentation. Sage holds a Bachelor's degree in Law and Justice Studies with a minor in Business Administration from Rowan University and is OSHA 10, Xactimate Level One, and FEMA certified, as well as a Haag Certified Reviewer.

Usually covered if the pipe burst suddenly. 9 claim tips, why claims get disputed, and the drying records adjusters ask for, from a restoration crew.
A burst pipe insurance claim usually turns on three things: what failed, how fast you acted, and what you can prove. We dry and document water losses across four states, so this guide covers the drying side of a burst or broken water pipe.
Does homeowners insurance cover a burst pipe? Usually, yes. A standard homeowners policy typically covers water damage from a pipe that bursts suddenly and accidentally, and often the cost to open walls or floors to reach it. It usually does not pay to replace the failed pipe itself, and it excludes gradual leaks, neglect, flood, and sewer backup unless you added an endorsement.
The NAIC describes coverage for "sudden and accidental" discharge from a plumbing system. The tear-out and failed-pipe points come from the standard ISO HO-3 form. Check your own declarations page and policy form for the exact wording.
- Sudden water damage is usually covered; the cracked pipe usually is not.
- Stopping the water and drying fast is a policy duty.
- Disputes usually turn on cause of loss and paperwork.
Burst pipe insurance claim tips: 9 steps that keep your claim on track
If water is still running, start with step 1. For a minute-by-minute version, see what to do in the first hour.
- Stop the water and make the area safe. Close the main shutoff valve. Stay out of standing water near outlets or cords, and if the electrical panel is wet, call the utility or an electrician first. Never walk under a ceiling bulging with water; it can drop without warning.
- Photograph and video the damage, without delaying water removal. Wide shots of every room, then close-ups of the break, stained ceilings, wet flooring and the water meter. Ten minutes is usually enough. Here is how to photograph and video the damage so the files hold up.
- Keep the failed pipe and get the plumber's note. Ask the plumber to save the burst section or fitting and to write down what failed and why. That note is often the main cause-of-loss evidence.
- Report the loss promptly. Standard policies list "prompt notice" among your duties after a loss, and the Pennsylvania Insurance Department tells homeowners to contact the insurer as soon as possible. Write down the claim number and the adjuster's name.
- Start professional drying and keep receipts. Your policy expects you to prevent further damage, and wet drywall and subfloor get worse while they sit. Professional drying also produces the first moisture readings, which become claim evidence. Water still spreading? (845) 294-8919, 24/7.
- Keep emergency and permanent repair costs separate. Plumbing, drying, rebuild, belongings and extra living costs often fall under different parts of the policy. Separate invoices are easier to approve.
- Don't discard damaged items until approved. Photograph them first, and keep samples of torn-out materials, such as a piece of carpet and pad.
- Keep a written claim log. Every call, email, inspection and amount, with dates and names.
- Get the moisture map and drying log. Readings from day one and each day after show how far the water went and when the structure reached dry.
What to have ready when you call
- Address, callback number and policy number (plus a claim number if you have one)
- The photos and videos you have so far
- Whether water is still running and the main valve is off
- Which rooms and floors are wet, including the ceiling below
Does homeowners insurance cover a burst pipe?
In most cases the damage the water causes is covered and the part that broke is not. The standard HO-3 form covers tearing out and replacing the part of the building needed to repair the system the water escaped from, but not the system itself. Wording varies, so check your declarations page and policy form.
Usually covered:
- Sudden and accidental discharge of water from the plumbing system
- Tearing out and replacing walls, ceilings or floors to reach the system the water escaped from
- Damaged belongings (Coverage C)
- Additional living expenses if the home cannot be lived in (Coverage D)
Usually not covered:
- The failed pipe, fitting or fixture itself
- Repeated seepage or leakage over weeks, months or years
- Wear and tear, deterioration and neglect
- Freeze damage in a vacant or unoccupied home, unless the heat was kept on or the water was shut off and drained
- Flood
- Water backing up through sewers or drains, unless you bought that endorsement
One distinction trips people up. A broken drain or waste pipe inside the house is generally treated as an accidental discharge from the plumbing system, like a cracked supply line. The separately excluded peril is water that backs up from outside the system through sewers or drains, which a backup endorsement adds. The cleanup differs too; see our sewer backup service.
What the claim pays for under a standard HO-3 policy (check your own declarations page):
| Cost | Usually falls under | Note |
|---|---|---|
| Emergency plumbing repair | Usually you | The pipe itself is excluded |
| Access and tear-out | Coverage A (dwelling) | Opening walls or floors to reach the break |
| Water removal and drying | Coverage A (dwelling) | Extraction, equipment, antimicrobial |
| Rebuild | Coverage A (dwelling) | Depreciation holdback may apply |
| Belongings | Coverage C | Furniture, clothing, electronics |
| Hotel, meals, temporary heat | Coverage D (loss of use) | Subject to limits; ask first |
How much do burst pipe claims pay?
The Insurance Information Institute (Triple-I) puts the average water damage and freezing claim at about $15,400 (2019-2023, a category that also includes covered mold). That average covers all homeowners water and freeze claims, not only burst pipes, and excludes adjustment expenses. For frozen pipes, State Farm reported more than 20,000 freeze-related water damage claims from 2024 through June 2025, with an average payment above $30,000: one insurer's numbers, not a national average.
Valuation matters too. Replacement cost value (RCV) pays to repair or replace with like kind and quality, but many insurers pay the depreciated amount first and release the rest after the work is invoiced. Actual cash value (ACV) pays only the depreciated amount. So ruined ten-year-old carpet on an ACV policy pays far less than new carpet costs. For typical line items, see our cost breakdown.
How a burst pipe claim moves: from first call to final payment
Most burst pipe claims run in two phases: mitigation (stop, remove and dry), then reconstruction once the adjuster agrees on scope. Each stage leaves records that carry the claim forward.
| Stage | Records it produces |
|---|---|
| Emergency | Photos, video, plumber's invoice and cause note, the failed part |
| Notice to the insurer | Claim number, adjuster's name, your claim log |
| Mitigation | Moisture map, daily drying log, equipment list, invoice |
| Adjuster inspection | Adjuster's notes, request for documents |
| Scope agreement | Insurer's and contractor's estimates, compared line by line |
| Rebuild | Contract, change orders, completion photos, final invoice |
| Depreciation recovered (RCV) | Final invoice sent to the insurer, holdback payment |
Timelines depend on your policy and your state's claim-handling rules, so ask the adjuster what happens next and when.
Proof of loss. Many homeowners policies ask for a signed, sworn proof of loss within 60 days after the insurer requests it, not 60 days after the loss. In New York, Insurance Law § 3407 says a missing proof of loss does not void the claim unless the insurer first sent written notice asking for it, with blank forms; returning it within 60 days of that notice counts as on time. Other states differ, so read your policy's conditions.
What the adjuster looks for (and what to say)
The adjuster has two questions: is this a covered loss, and how big is it? Everything you hand over should answer one of them.
| The adjuster checks | What you hand over |
|---|---|
| Cause of loss | The failed part and the plumber's note |
| Date of loss | Time-stamped photos and video |
| Signs of a long-term leak | Readings showing a sharp wet/dry boundary |
| Whether you mitigated | Restorer's invoice and equipment log |
| Scope of damage | Moisture map, drying log, photos of every cut |
| Belongings | Inventory with photos |
What to say (general guidance, not legal advice):
- What you saw and did, in order, and when you found the water.
- Point to the plumber's note and the restorer's readings.
- Ask for every request in writing, and send documents by email so there is a record.
What to avoid:
- Guessing at the cause or how long it leaked.
- Signing a release, or endorsing a check marked "final," before scope is agreed.
- Signing an assignment of benefits or direction to pay you have not read. You can usually authorize direct billing without assigning your claim; rules vary by state.
For a contested denial, a licensed public adjuster or an attorney is the right call.
Questions to ask your adjuster
- RCV or ACV, and how is depreciation held back and recovered?
- What is my deductible, and is there a water sublimit or separate water deductible?
- Is tear-out and access to the leak included? Is there a mold sublimit?
- Will you pay the mitigation company directly?
- Does loss of use cover a hotel or temporary heat?
- How do I dispute the estimate?
Why burst pipe claims run into problems
Most disputes are not about whether water damage happened. They are about when it started, whether it was preventable, and how much has to be replaced.
Sudden vs gradual: the line insurers draw
Most homeowners policies exclude water that leaked or seeped repeatedly over weeks, months or years. Some insurers' forms name a specific period, such as 14 days; in 2018 a Florida appeals court (Hicks v. American Integrity, 241 So.3d 925) read one such clause as not clearly excluding leakage of 13 days or less. Some forms also carve out a leak hidden inside a wall, ceiling or floor that no one in the household knew about (the exception in the 2011 ISO HO-3 form). Read the exclusions in your own policy.
| Usually treated as sudden | Usually treated as gradual |
|---|---|
| A copper line that splits in a freeze | Pinhole leaks in copper dripping for years |
| A fitting that blows off | A slab leak seeping for months |
| A supply line that bursts under a sink | A corroded galvanized line weeping at the joints |
Freezing is a classic sudden cause: ice is about 9 percent less dense than liquid water, according to the USGS, so water freezing in a closed pipe needs more room than the pipe has. When timing is questioned, these signs point to a recent event:
- Readings that drop off sharply a short distance from the failure point
- No tide lines or layered staining
- No decay or soft spots in framing or subfloor
- A fresh, uncorroded break face on the failed part
In older homes, maintenance records help. Older plastic systems such as polybutylene draw extra scrutiny, so keep any inspection or replacement paperwork.
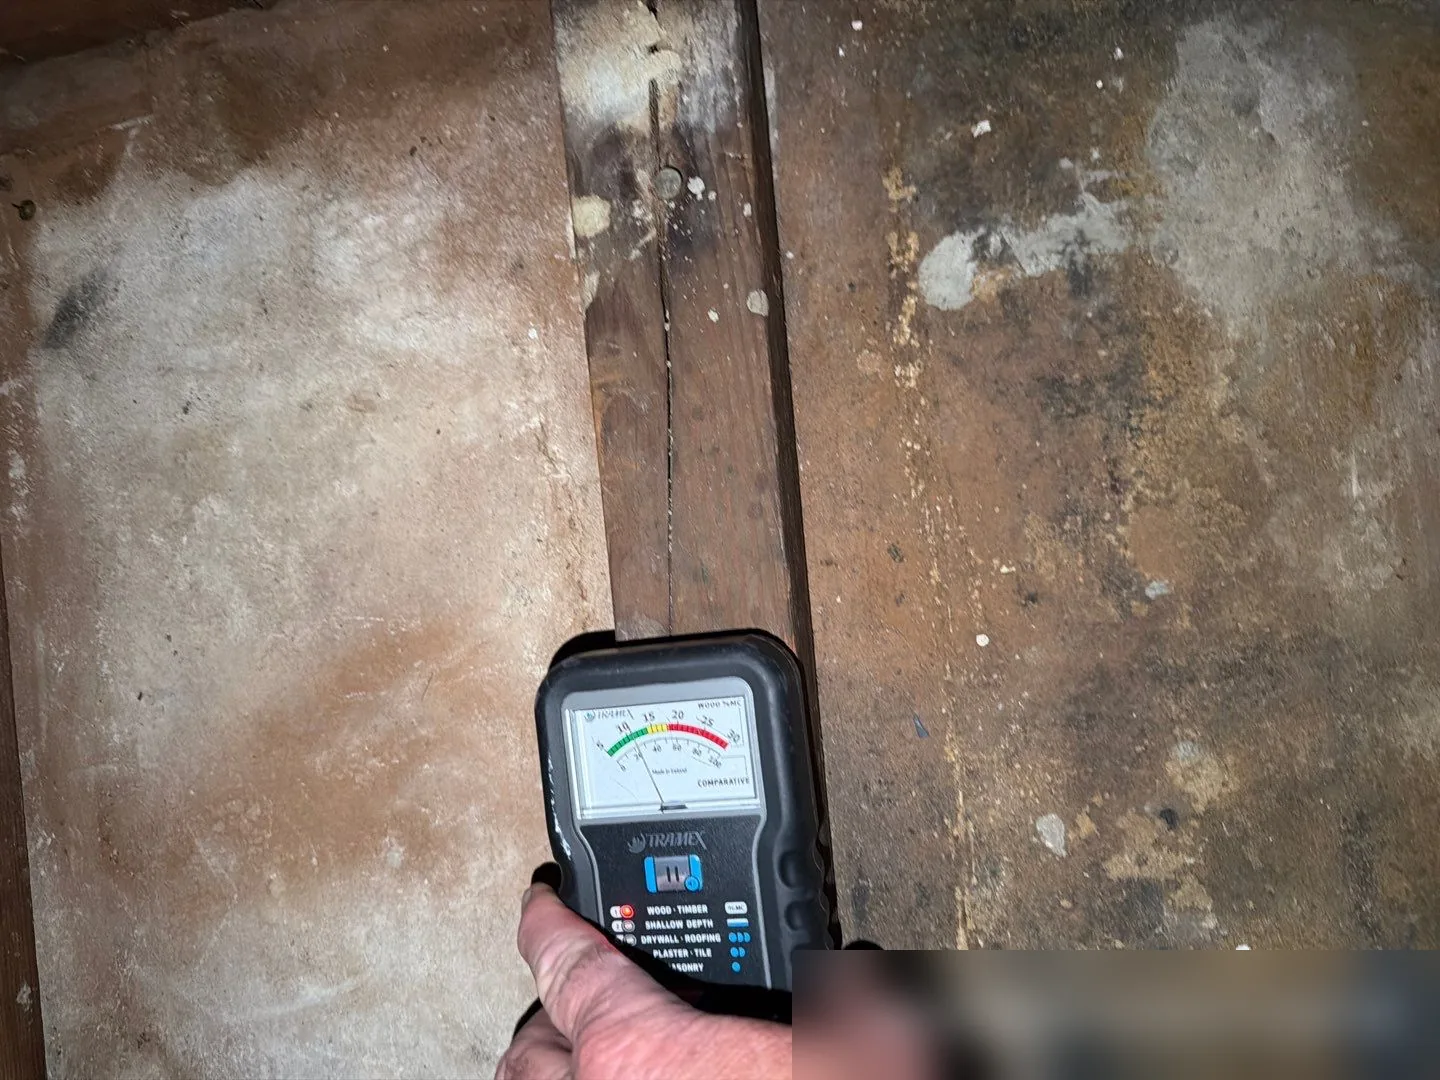
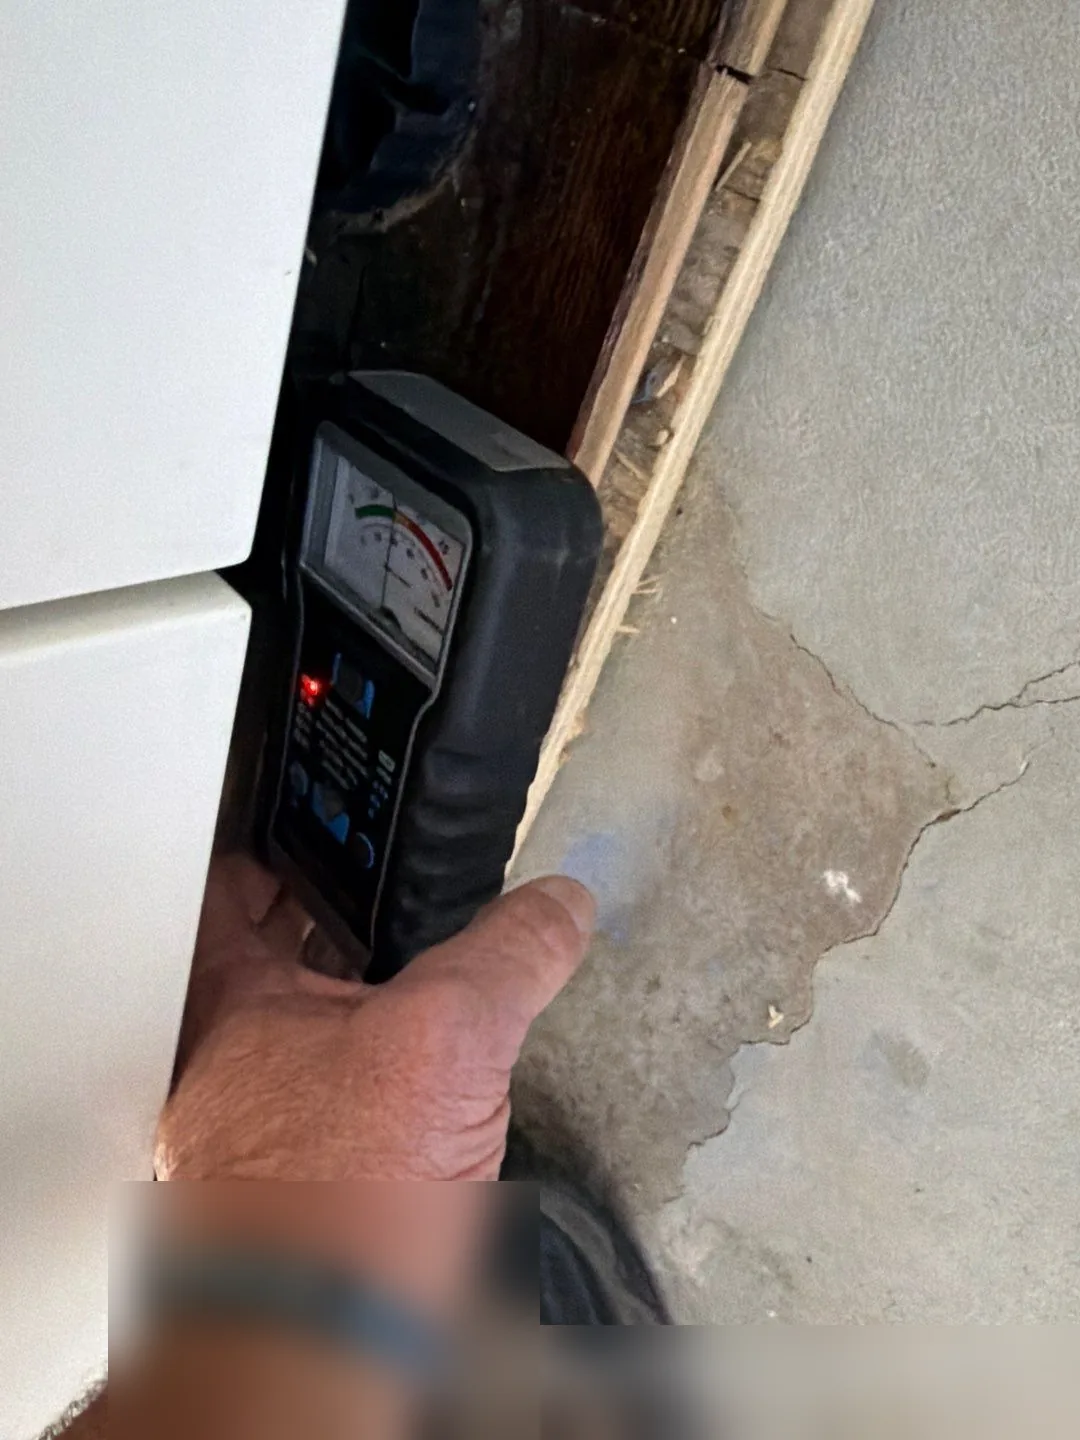
The photo shows that kind of reading: the meter on the stained underside of the subfloor between joists. Crews read outward from a spot like this until the numbers return to normal, and a tight wet zone around the source supports a recent leak.
Vacancy, heat and "reasonable care"
The standard HO-3 freezing condition applies while the home is vacant, unoccupied or under construction, and it sets no minimum number of days. During that time, freeze damage is covered only if you used reasonable care to keep the heat on, or shut off the water and drained the system and appliances. A weekend away with the thermostat turned off can be enough to put a claim at risk. The NAIC likewise ties coverage to "reasonable steps." Some policies add separate vacancy limits, so check both clauses.
Late notice and failure to mitigate
Waiting a week to report, or leaving wet carpet in place, lets the insurer argue that part of the damage came from the delay. The answer is records: the date you called, the mitigation invoice, and a drying log showing equipment went in early.
Concealed damage and mold
Water runs along joists, into wall cavities and under flooring. Spaces never opened or measured can surface weeks later as stains, odor or mold, and the timing question returns. The EPA advises drying water-damaged areas and items within 24-48 hours to prevent mold growth; that is guidance, not a guarantee. Many policies cap mold under a sublimit. When mold growth after a leak needs removal, the work follows ANSI/IICRC S520.
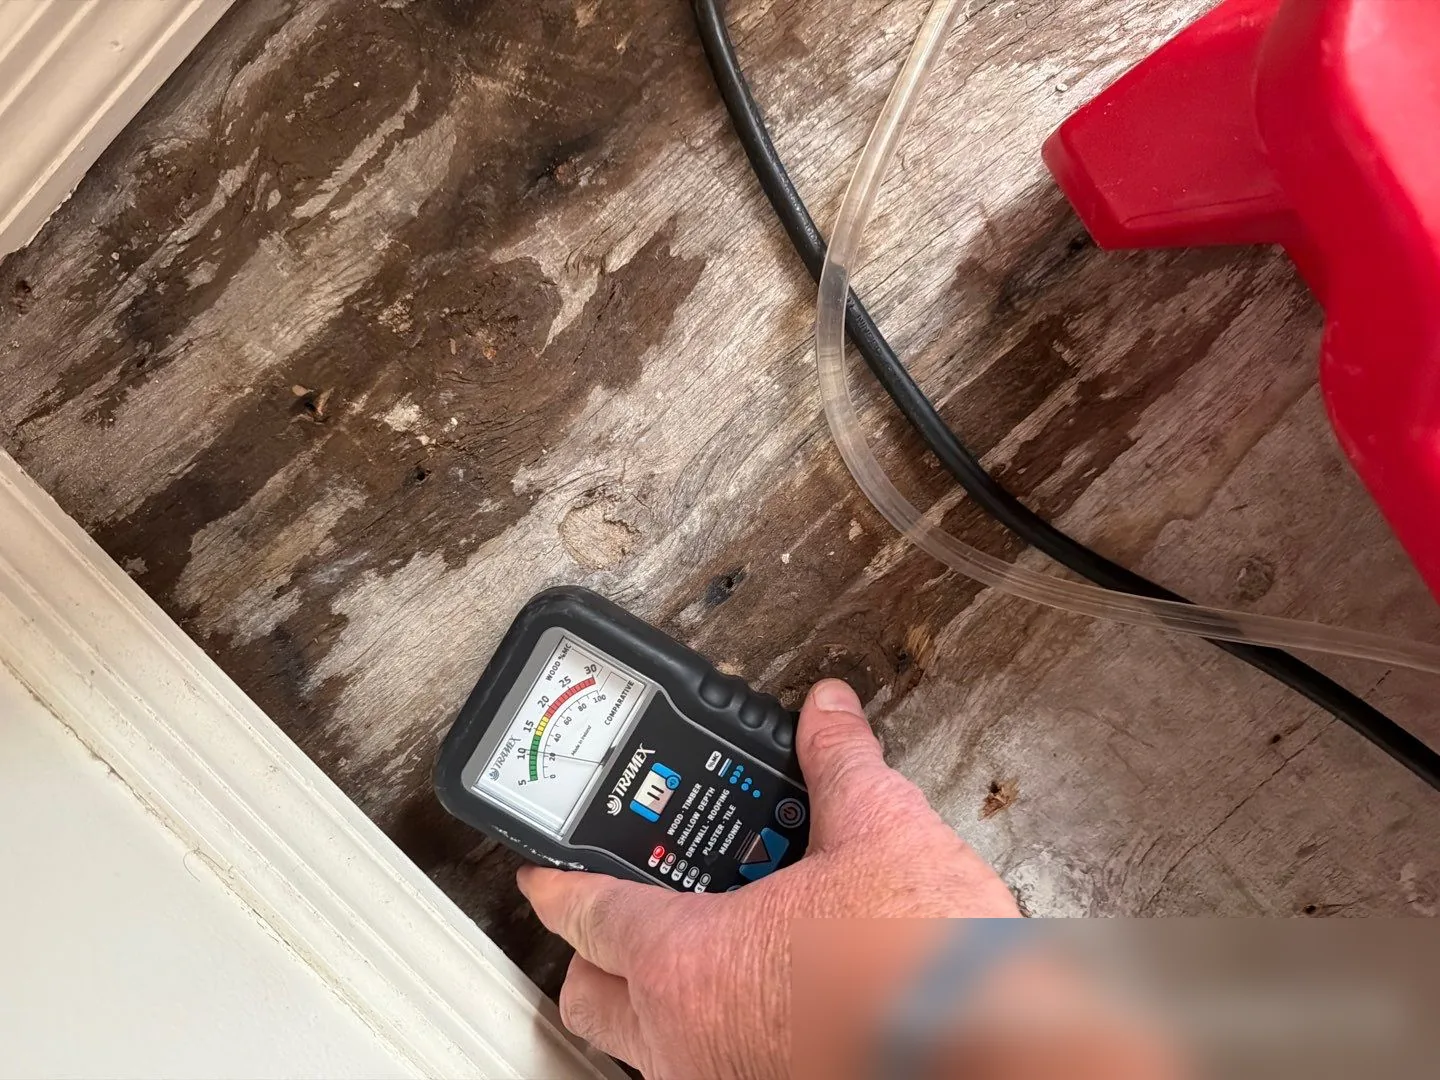
Here the finished floor is already off and drying equipment runs beside the stained subfloor. Hidden damage shows up first in places like this, so crews keep reading it until it is dry.
Depreciation, scope and matching disputes
Many money disputes are smaller than a denial. The RCV holdback sits unpaid because no final invoice was sent. The estimate leaves out baseboards, insulation, or painting the whole room. Or the policy pays for damaged flooring but not matching the undamaged floor next to it. Compare estimates line by line, and ask in writing how matching works under your policy.
How restoration records settle scope disputes (IICRC S500 in plain English)
Scope disputes are about how much was wet and what had to come out. We follow ANSI/IICRC S500 procedures, and the records that standard calls for answer exactly that. More background: IICRC S500 drying standards.
Water category and class
Category describes contamination. Category 1 is clean water, such as a broken supply line, and it can degrade to Category 2 or 3 with time, temperature and contact with building materials or contaminants. Water from a broken drain or waste line carrying sewage is treated as Category 3 from the start. Class describes how much water has to evaporate, based on how much wet, porous material is involved. The restorer records the category at the first inspection, and that record drives what is removed and what is dried in place.
Moisture mapping, drying logs and drying goals
On day one the crew takes moisture readings across walls, floors and ceilings and marks where wet ends. They also read the same materials in an unaffected room; that dry standard becomes the drying goal. Readings and equipment counts are logged daily until the goal is reached.
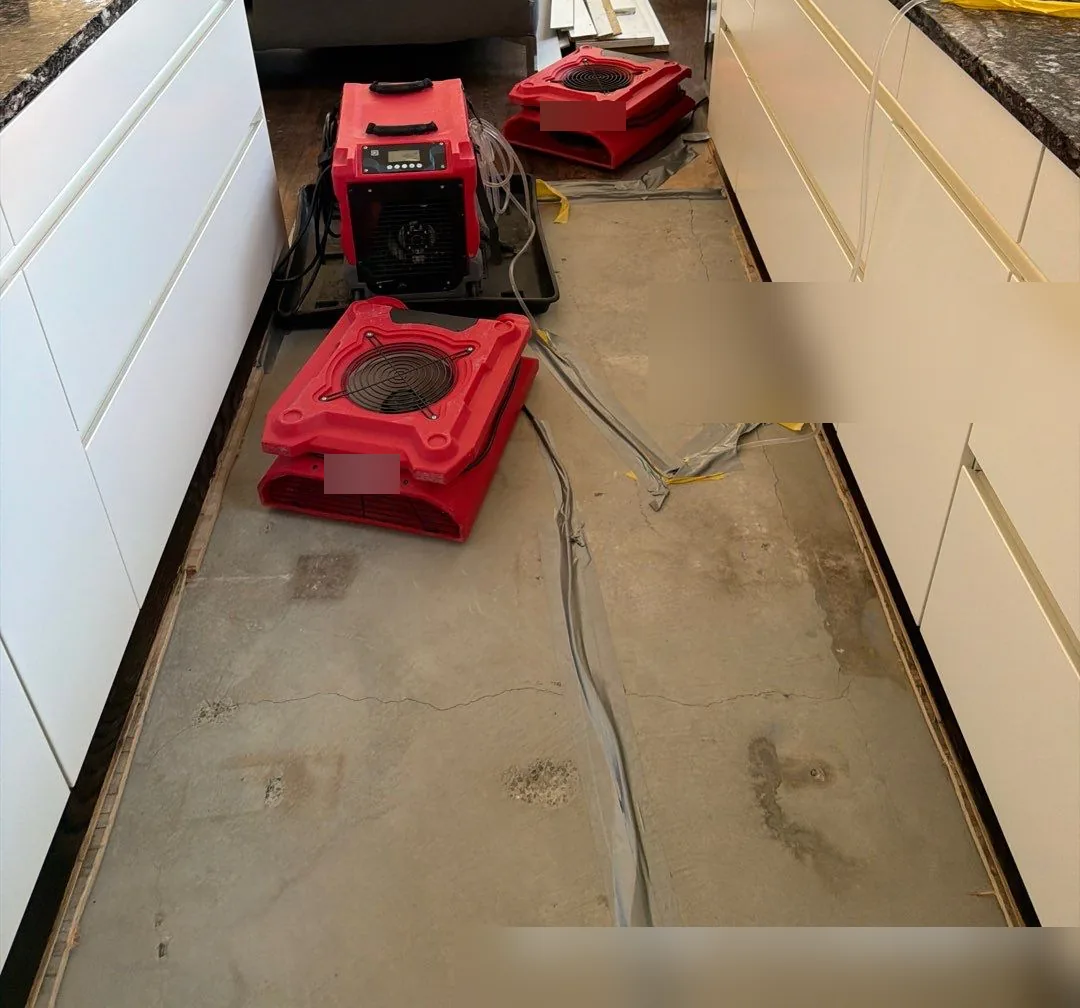
In this kitchen the flooring is off down to the slab, with air movers and a dehumidifier along the cabinet run. A setup like this goes into the drying log; see dehumidification and structural drying for how it works. An adjuster or appraiser can check which walls were wet, how long equipment ran and why each cut was made. Readings settle scope arguments far better than memories.
Working with your insurer
You choose the contractor; the insurer may suggest a network vendor, but in most cases you do not have to use one. Your restorer can share photos, readings and estimates with the adjuster. Direct payment depends on your policy and what you authorize in writing. Ask us for the moisture map and drying log for your adjuster.
Special situations
If the pipe burst while you were away
Is a burst pipe covered if it happened while you were away? Often, yes, if you took reasonable care. Standard policies expect an empty home to be kept heated, or the water shut off and the system drained. If the heat was off and the water was not shut off and drained, insurers can deny the freeze damage. Some policies also add vacancy limits, so check both clauses.
Collect proof the house was heated: smart-thermostat history, utility bills, a neighbor's notes. If the burst pipe was inside a wall, check for the hidden-leak exception above and the signs of a leak hidden behind the wall.
Heat, ALE and temporary heating
Water damage from a frozen pipe is usually covered, while the plumber's bill for the burst pipe itself is usually yours. A furnace or boiler that simply quit is generally a breakdown or maintenance issue, unless your policy includes an equipment breakdown endorsement. Loss of use may pay extra living costs if the home is unlivable, and temporary heat during drying can be part of mitigation; ask the adjuster first. We can provide emergency heating while the home dries.
Condos, co-ops, apartments and rentals
The building's master policy usually covers common elements, a unit owner's HO-6 covers the finishes and fixtures the governing documents assign to the owner, and a renter's HO-4 covers the tenant's belongings. In New York co-ops and in New York and New Jersey condos, the proprietary lease or bylaws often put fixtures and finishes on the unit owner, but documents differ, so check yours. Renters: see who pays, landlord or tenant and apartment water damage. For units in Manhattan and the other boroughs, our water damage restoration in New York City crew is based in Midtown.
Flood policy vs homeowners policy
FEMA defines a flood as "a general and temporary condition of partial or complete inundation of 2 or more acres of normally dry land area or of 2 or more properties (at least 1 of which is the policyholder's property)" from causes such as overflowing water or mudflow (FEMA glossary). Water from your own broken pipe is not that, so it is a homeowners loss. When a storm and a pipe break happen together, document each water source separately.
Should you file for a small leak?
Compare the estimate for the burst pipe damage with your deductible, but get moisture readings first: a leak that looks minor often wets more drywall and subfloor than expected. A claim can affect your premium or renewal, so ask your agent how your insurer treats water claims.
Burst pipe claims in New York, New Jersey, Pennsylvania and Connecticut
Long freezing spells and plumbing in unheated spaces make winter pipe breaks common across our region. The claim process is the same in all four states; the regulator, public adjuster rules and contractor registration are not.
- New York: The Department of Financial Services licenses public adjusters, whose fee by law may not be higher than 12.5% of the recovery. New York City requires a Home Improvement Contractor license.
- New Jersey: The Department of Banking and Insurance takes insurance complaints; check a public adjuster's license there and read the fee clause. Contractors register with the Division of Consumer Affairs.
- Pennsylvania: The Insurance Department tells consumers to ask anyone presenting as a public adjuster for licensing information. Most contractors must register with the Attorney General's Office under the Home Improvement Consumer Protection Act. See also our Pennsylvania water damage claim guide.
- Connecticut: The Insurance Department takes complaints and licenses public adjusters. Contractors register with the Department of Consumer Protection.
For the deadline to sue, see your policy's "Suit Against Us" clause and ask the regulator if it is unclear. If the pipe broke anywhere in these four states, our crews answer at (845) 294-8919 around the clock.
Public adjusters and appraisal
A public adjuster works for you for a percentage of the payment, which suits large or disputed losses more than a small claim already being paid. Check the license and ask whether the fee applies to money already offered. Most policies also have an appraisal clause: if you agree the loss is covered but not on the amount, each side picks an appraiser and the two choose an umpire. Moisture maps and drying logs are the evidence it runs on.
Before the next freeze: policy check and prevention
Policy check: water backup endorsement, water sublimit or deductible, mold sublimit, RCV or ACV, vacancy and freezing conditions, loss-of-use limit.
Prevention, drawn from the NAIC's list and insurer advice:
- Insulate exposed pipes in attics, crawl spaces and outside walls; seal exterior gaps.
- Keep the heat on. State Farm advises at least 55°F.
- In extreme cold, let faucets drip and open cabinet doors under sinks.
- Know where your main shutoff valve is.
- Consider leak sensors or an automatic shutoff valve; some insurers offer discounts.
Frequently Asked Questions
Will insurance replace the burst pipe itself?
Usually not. Standard forms exclude the system the water escaped from, so the burst pipe, fitting or water heater is treated as your repair. What they usually cover is the water damage, plus tearing out and replacing walls or floors to reach the break. Service-line or equipment breakdown endorsements can change this, so check yours.
How long do I have to report it?
Policies ask for "prompt" notice, so report the same day if you can. Proof of loss is a separate step: standard forms often ask for a signed, sworn proof of loss within 60 days after the insurer requests it, not after the pipe broke. Your policy and state rules set the exact terms.
Can I choose my own restoration company, or must I use the insurer's?
In most cases you can choose your own. An insurer's network vendor is usually a suggestion, not a requirement. Whoever you hire, have them share photos, moisture readings and the estimate with the adjuster so scope is agreed on the same evidence.
Who pays the restoration company, and when is the deductible due?
It depends on your policy and what you sign. Some insurers pay the restorer directly with your written authorization; others reimburse you. The deductible is subtracted from the claim payment. Read any direction to pay before signing, and ask what happens if the insurer pays less than the invoice.
Does insurance pay to find the leak or open the wall?
Often, yes. Standard HO-3 wording covers tearing out and replacing the parts of the building needed to repair the system the water escaped from, which usually includes opening a wall or ceiling to reach the leak. Ask the adjuster first when you can, and photograph before and after.
Is mold covered after a burst pipe?
Often only up to a mold sublimit, and only when the mold grew from a covered water loss. Mold found weeks later reopens the timing question, so ask the adjuster about the sublimit early and keep the drying log that shows when each area reached dry.
Do I need a plumber's report for the claim?
It is strongly advisable. A short written note saying what failed and why is usually the main evidence of cause. Keep the failed part in a labeled bag until the claim closes; together, the part and the note are hard to argue with.
Before you let anyone open a wall
Get the moisture mapped first. Once drywall is cut and hauled away, the only record of how far the water went is the readings and photos taken before the cut. If water is still moving, call (845) 294-8919; crews typically arrive within 90 minutes in nearby service areas. Or contact our 24/7 team online.
This guide explains how claims usually work. Your policy wording and your state's rules decide your claim, so read both or ask a licensed professional.
Categories
Need Restoration Services?
Our team is available 24/7 for emergency response. Call us today for a free phone consultation.
Questions About Restoration?
Our experts are ready to help. Contact us for a free consultation.